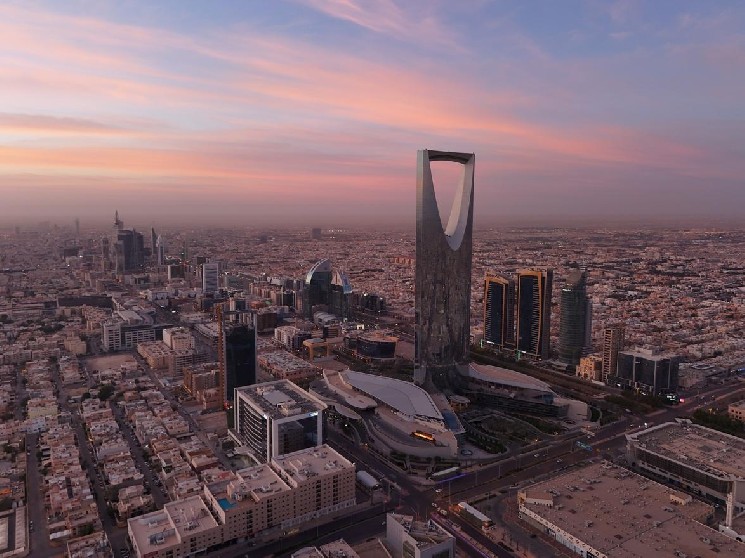
De-dollarisation is the wrong file for it. Saudi Arabia holds $142.4 billion of US Treasuries, up $11 billion in a year, pegs its currency to the dollar and prices its oil in it, and the RMB 50 billion swap line it signed with the PBoC in November 2023 has not visibly changed that. What the exit does show is what “live” has meant on the platform since June 2024.
Eight transactions a day
mBridge is, by some distance, the most advanced multi-currency CBDC platform in existence. It began as Inthanon-LionRock, a Hong Kong-Thailand corridor prototyped in 2019. The PBoC and the UAE joined in February 2021 and the BIS Innovation Hub took it over. A six-week pilot in 2022 put 20 commercial banks on it and settled 164 payment and FX transactions worth just over $22 million, or THB 827 million in the Bank of Thailand’s accounting. The MVP went live in June 2024. The BIS left in October 2024, its general manager Agustín Carstens saying the BIS had “graduated out,” that mBridge “is not the ‘BRICs bridge’,” that “whatever products we put together should not be a conduit to violate sanctions,” and, in the same remarks, that the platform was “not mature enough to start operating” and “many years away from that.” Macau joined this June, with three of its eleven approved banks settling 23 transactions worth nearly MOP 13 billion on the first day.
Beijing has released the throughput. State television reported in January that from the start of trial operation in June 2024 to the end of 2025 the platform processed 4,868 cross-border payments worth RMB 477.8 billion, about $67 billion, with the digital yuan accounting for roughly 96% of the value. Mu, who runs the PBoC’s Digital Currency Institute, restated the end-2025 figure as “nearly RMB 500 billion” in June and said 49 commercial banks, 21 of them foreign, were connected. The Atlantic Council, working from a PBoC post giving figures to the end of November, counted about $55.49 billion and a 95.3% digital-yuan share.
On the figure Beijing has released, 4,868 transactions over about 575 days is eight or nine a day, and $67 billion is what CLS, which settled an average of $7.9 trillion a day in the first half of 2025, clears in about twelve minutes. It is twenty-one minutes of Fedwire and forty-eight minutes of CHIPS. Hong Kong’s own renminbi real-time gross settlement system moves RMB 2,516 billion a day, so it would clear mBridge’s entire nineteen-month history before the end of the afternoon. The digital yuan itself had processed RMB 16.7 trillion of transactions by last November; the bridge in the de-dollarisation story accounts for under 3% of it. Bank of China, one participant, says its own cumulative mBridge transactions passed RMB 600 billion by June 2026, which would mean either that volume has accelerated sharply this year or that both legs of the same payment are being counted. The platform has published no 2026 figure.
The technology is not the problem. The 2021 prototype report found that international transfers and foreign-exchange operations could be completed “in seconds” and their cost “reduced by up to half,” and nothing since suggests otherwise. What the network diagrams leave out is the counterparty. A settlement platform is worth nothing until the party being paid is on the other end of it, and Saudi Arabia’s counterparties are paid in dollars through New York.
Why 96% is yuan
The digital yuan is the only currency on the platform with a large number of counterparties behind it. The UAE made the first cross-border Digital Dirham payment, AED 50 million to China, in January 2024, has disclosed one government transaction since, and has published no volume. The HKMA’s 2025 annual report mentions mBridge once, in a sentence about “tangible results,” with no figure attached. The Bank of Thailand’s page on it still says the project “will continue building and testing.” Take any non-Chinese participant and the traffic is mostly Chinese banks paying Chinese counterparties in yuan, which is a domestic system with a foreign-exchange window.
For Saudi Arabia the calculation was never close. Its oil sales are priced in dollars, and a yuan-settlement rail is useful only if Riyadh wants to accumulate yuan, which is what the swap line exists to avoid. The Wall Street Journal reported in March 2022 that Riyadh was considering accepting yuan for some Chinese oil sales; Fortune’s word for it this week was “flirted.” A proof of concept “without any real financial transactions” is the same posture: present in the room, with no trade on the record.
Sibos opens in Miami next week and the tokenised-corridor releases will come in bulk. Each should be read for transactions rather than members, and for who is on the other side of them. By that measure mBridge, with 49 banks and eight payments a day, is still the most successful thing in its category. The BIS’s Project Agorá, its own successor bet, launched in April 2024 with seven central banks and now has eight and more than 40 firms; its real-value testing this summer involved 28 institutions and approximately CHF 800,000 across 17 scenarios. Project Nexus, the instant-payments linkage the BIS incubated for Southeast Asia, appointed a technical operator in February and targets going live in 2027. Projects Dunbar, Jura and Mariana were prototypes and reported no throughput. Fnality and Partior, the private-sector versions, publish no volumes at all.
Supervision left with the BIS
Supervision has had less attention than membership. When the BIS handed mBridge to its participants in October 2024, the structure lost its only multilateral institution. The platform is now run by its member central banks, one of which supplies 96% of the traffic. Since the BIS left, the only figures on what runs across it have come from the PBoC, on WeChat, on state television and at a Davos panel. Carstens’s assurance that BIS products cannot be used by sanctioned countries was true on the day he gave it and expired the day the BIS left.
Saudi Arabia’s exit leaves the platform as it was and shortens the list of who can be said to endorse it. The Gulf’s largest economy has now said in writing that it was never more than a limited participant, that it moved no money on the platform, and that it left the moment its test was done. The UAE remains, with two disclosed payments and no published volume. What is left is a live cross-border central-bank settlement system dominated by one central bank, with no multilateral overseer, and a membership list that reads better than its ledger.
What to watch
The PBoC either publishes a full-year 2026 figure or it does not, and if it does it has the Bank of China number to explain. The UAE and Hong Kong have yet to disclose a non-yuan volume. Any of the “more than 26 observing members” the BIS listed in 2024 can follow Macau in, or Saudi Arabia out. SAMA’s statement that it “did not join any subsequent phases” is an invitation to ask the others the same question. The CBUAE, which calls mBridge “the world’s first operational multi-CBDC platform,” has not said what it has operated.
The technology works. Eight or nine payments a day, almost all of them in yuan, is the demand for it, and Saudi Arabia’s was zero.