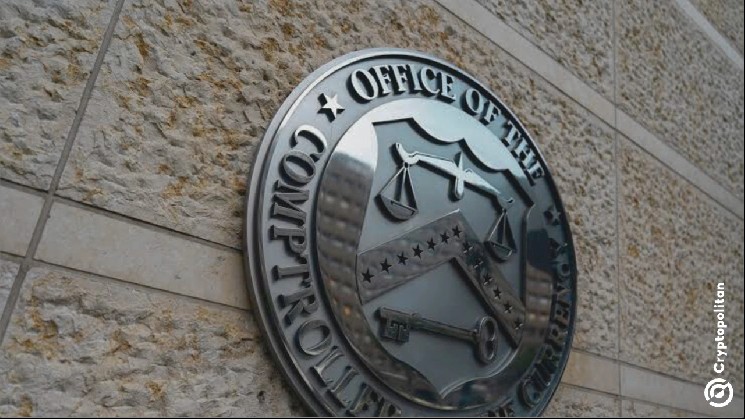
The licensing scheme will be effective from January 18, 2027. From this date onwards, it will become mandatory for any entity to seek prior approval from the OCC before issuing a payment stablecoin. Failure to do so can lead to criminal consequences.
Why the OCC wants banks in the game
Jonathan V. Gould, Comptroller of the Currency, presented the rulemaking process as a way for the agency to return to its roots. “In implementing the $GENIUS Act and supervising stablecoin issuers, we are reminded of where we come from and the responsibility we have for facilitating financial innovation,” said Gould in his Monday post on X, PYMNTS reports. In addition, he noted that “this final rule establishes a federal framework that allows stablecoins to fulfill their potential while advancing the dollar’s dominance.”
Further, the agency referred to the drive to its Community Bank Comeback Initiatives that the agency claims are designed to balance the regulation for smaller institutions so they could keep meeting their customers’ needs. In order to reduce concerns of small banks, the regulator released a fact sheet which highlights two key points: community bank deposits can be eligible reserve assets for stablecoins; supervision will be scaled appropriately to the risk profile of each individual issuer.
If the number of small lenders participating in this process is sufficient, they may significantly reduce the market share of stablecoins currently owned by crypto companies and large financial institutions.
$850 billion lending worry
Not all banks will be sold, however. The Independent Community Bankers of America opposed the trend toward stablecoins, estimating that their adoption could limit the lending capacity of community banks by almost $850 billion. The logic behind such a stance is that the deposits, which serve as a source for local loans, would instead go into stablecoins.
The OCC’s implicit response to such objections is that banks can issue stablecoins themselves and use deposits as reserves. There is more at stake than just a question of regulation here. Last month, the ICBA sued the OCC, arguing that crypto companies that got the charter approvals had an advantage since they were not subjected to the same regulatory requirements as community banks.
The clock is now ticking against everyone, however. The existing issuers, which have a substantially complete application submitted by the compliance deadline, can get a temporary waiver for up to 12 months, effectively extending the period until approval by one year instead of stopping immediately. To get such a waiver, banks should submit their applications before January 18, 2027.