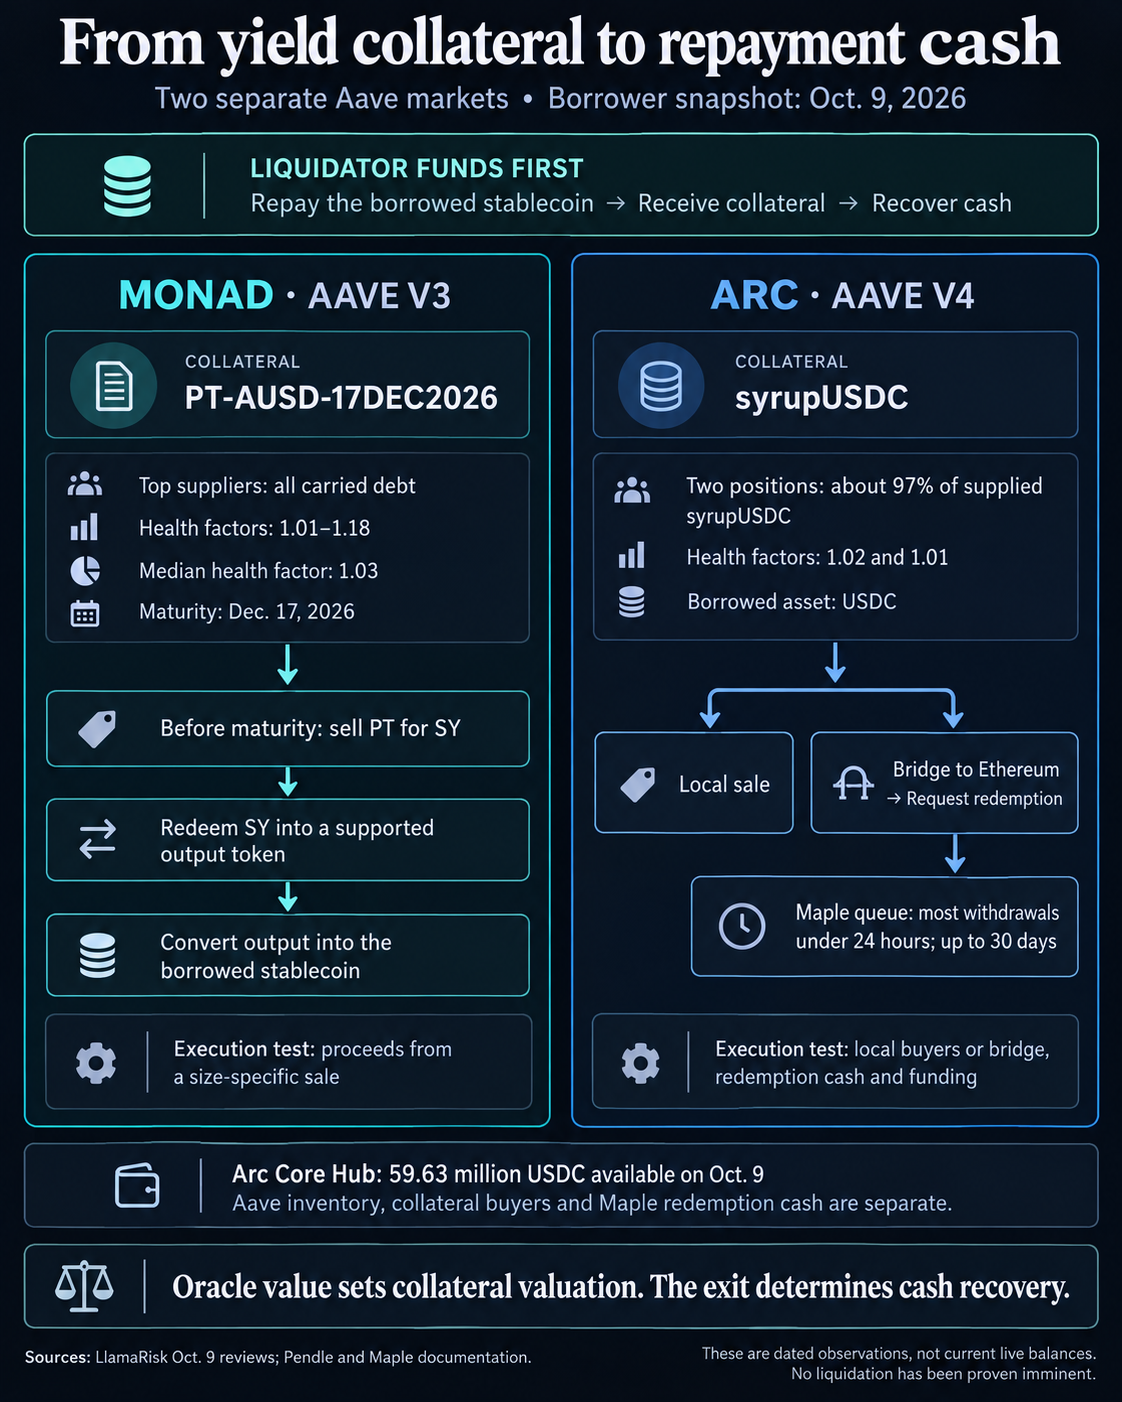
Aave’s health factor compares collateral value, adjusted for liquidation thresholds, with debt. A position becomes eligible for liquidation below 1. The top Monad PT suppliers had health factors between 1.01 and 1.18, with a median of 1.03, in the Oct. 9 snapshot. $USDC was their dominant debt asset, followed by USDT0.
Those readings leave a narrow valuation cushion for part of the cohort. They also reflect why borrowers pair correlated collateral and debt: smaller relative price changes can support higher leverage. Aave notes that lower health factors may be appropriate for correlated assets.
During liquidation, someone repays the borrower’s debt and receives collateral plus an incentive. The liquidator weighs the collateral’s realizable proceeds against the debt repaid, transaction and conversion costs, and the cost of financing any redemption wait. The health factor measures proximity to eligibility; a sale quote measures the exit.
Monad’s PT-$AUSD Aave loans need a sale before maturity
The Monad collateral is PT-$AUSD-17DEC2026, a Pendle principal token representing a claim on $AUSD at its Dec. 17 maturity. The redemption entitlement is in the accounting asset. Receiving one $AUSD still requires any conversion needed to obtain the $USDC or USDT0 borrowed against it.
LlamaRisk reported that the reserve’s 30 million PT supply cap was fully utilized on Oct. 9 and recommended increasing it to 60 million PT. These limits measure token capacity. A larger cap would allow more collateral into Aave; its successful exit would still depend on buyers or redemption.
Before maturity, Pendle’s documented liquidation route sells PT into SY, its standardized yield wrapper, then redeems SY into a supported output token. After maturity, PT can be redeemed into SY without that market sale. Any further conversion into the borrowed stablecoin remains part of the route.
The Oct. 9 review describes the Pendle pool as 47% PT and 53% SY. A large PT sale draws from the opposite side of the pool, so a useful exit estimate needs the intended sale size, output and price impact across the full conversion.
Pricing adds another constraint. LlamaRisk says the December PT uses a linear discount oracle on $AUSD/USD. Pendle’s linear-discount documentation describes a predictable path toward maturity independent of AMM prices. That valuation can follow its curve while a liquidator’s sale price depends on the market’s willingness to absorb seized PT.
LlamaRisk’s Oct. 2 launch recommendation specified a 95% liquidation threshold and a 2.62% bonus for the stablecoin E-mode, alongside a 93% borrowing limit. A liquidator has to compare the incentive applicable at execution with the actual cost of turning PT into the debt token.
Arc’s syrupUSDC Aave loans rely on buyers or a redemption queue
The Arc comparison concerns syrupUSDC, a bridged share in Maple’s Ethereum yield-bearing vault. In the Oct. 9 Arc review, the two largest positions held approximately 97% of the supplied syrupUSDC at health factors of 1.02 and 1.01. All outstanding debt among syrupUSDC suppliers was $USDC.
A few positions can therefore dominate demand for that collateral’s exit. The concentration refers to supplied syrupUSDC, while the stablecoin available to Aave lenders sits in a separate reserve.
Arc had substantial Aave liquidity at the snapshot: 143.45 million $USDC added to the Core Hub, 83.82 million drawn and 59.63 million available. That available balance is debt-token inventory in Aave. Buyers of syrupUSDC and cash available for Maple redemptions determine other parts of the unwind.
LlamaRisk’s September Arc assessment, using Sept. 23 liquidity data, found one local Uniswap V4 syrupUSDC/$USDC venue whose proceeds saturated near $500,000 as its $USDC side was exhausted. The sale ran into the venue’s available cash inventory.
The same assessment described no native Arc redemption. A holder could sell locally or bridge to Ethereum and then request redemption. It estimated the bridge transfer alone at two to five minutes under normal conditions, with throughput around $10 million an hour. Maple’s withdrawal queue adds a separate wait.
Maple’s withdrawal terms make the timing constraint explicit: requests enter a first-in, first-out queue and are processed as liquidity becomes available. Most withdrawals take under 24 hours, but they can take up to 30 days. Its contract architecture explains why entitlement to a pool’s value can exceed immediately available withdrawal cash.
For a liquidator using that route, Ethereum redemption and Arc debt repayment are separate stages. The funder needs $USDC to repay the Aave loan before the collateral’s later exit pays them back. Bridge capacity, redemption cash and financing duration each affect whether the unwind is economical.
Arc’s shared Hub connects lender exposure with cap growth
LlamaRisk’s Arc onboarding recommendation values syrupUSDC through Chainlink’s syrupUSDC/$USDC exchange rate and capped $USDC/USD using a CAPO adapter. The exchange-rate input follows the Ethereum vault’s exit value. Local trading depth determines how much of that value a sale can realize.
The recommendation also specifies a 92% collateral factor and a dynamic liquidation bonus capped at 4%. The applicable bonus varies with the liquidation conditions. Its maximum provides a ceiling on the incentive against which a liquidator weighs exit costs.
The Maple Spoke draws from the same Arc Core Hub $USDC reserve as the Main Spoke. Aave’s earlier Hub design discussion explains shared solvency inside a Hub: Spoke-level limits constrain exposure, while the Hub remains the common liquidity and accounting venue. Applied to the described Arc arrangement, that architecture places Maple Spoke exposure within the Core Hub’s shared solvency. Monad’s V3 market and Ethereum’s separate Hub configurations have different boundaries.
LlamaRisk’s Oct. 9 Arc proposal would increase the Maple Spoke’s $USDC draw cap from 23 million to 46 million $USDC and its syrupUSDC add cap from 25 million to 50 million shares. The draw cap was fully utilized and the add cap 87.8% utilized in that review. Share-token capacity requires its own valuation before comparison with dollar debt.
Those caps set maximum collateral or borrowing capacity; additional exposure depends on subsequent deposits and borrowing.
For lenders assessing these Aave loans, the test is concrete: compare recoverable collateral proceeds at the relevant liquidation size with the debt repaid and total exit costs, then identify who funds any redemption delay. The liquidation incentive affects how much collateral the liquidator receives. Monad’s PT requires a market sale before December maturity. Arc requires local buyers or an Ethereum exit with sufficient bridge capacity, redemption cash and financing.